Does Homeowners Insurance Cover Foundation Repair? (2026 Guide)
Research Highlights
Homeowners insurance covers foundation repair
only when a sudden, covered peril causes the damage: a fire, a windstorm, a fallen tree, a vehicle impact, or a burst pipe under the slab. Gradual damage from
settling, expansive clay soil, seepage, tree roots, or poor construction is excluded by virtually every standard policy, and insurers in Texas specifically exclude slab movement caused by soil. Flood and earthquake damage require
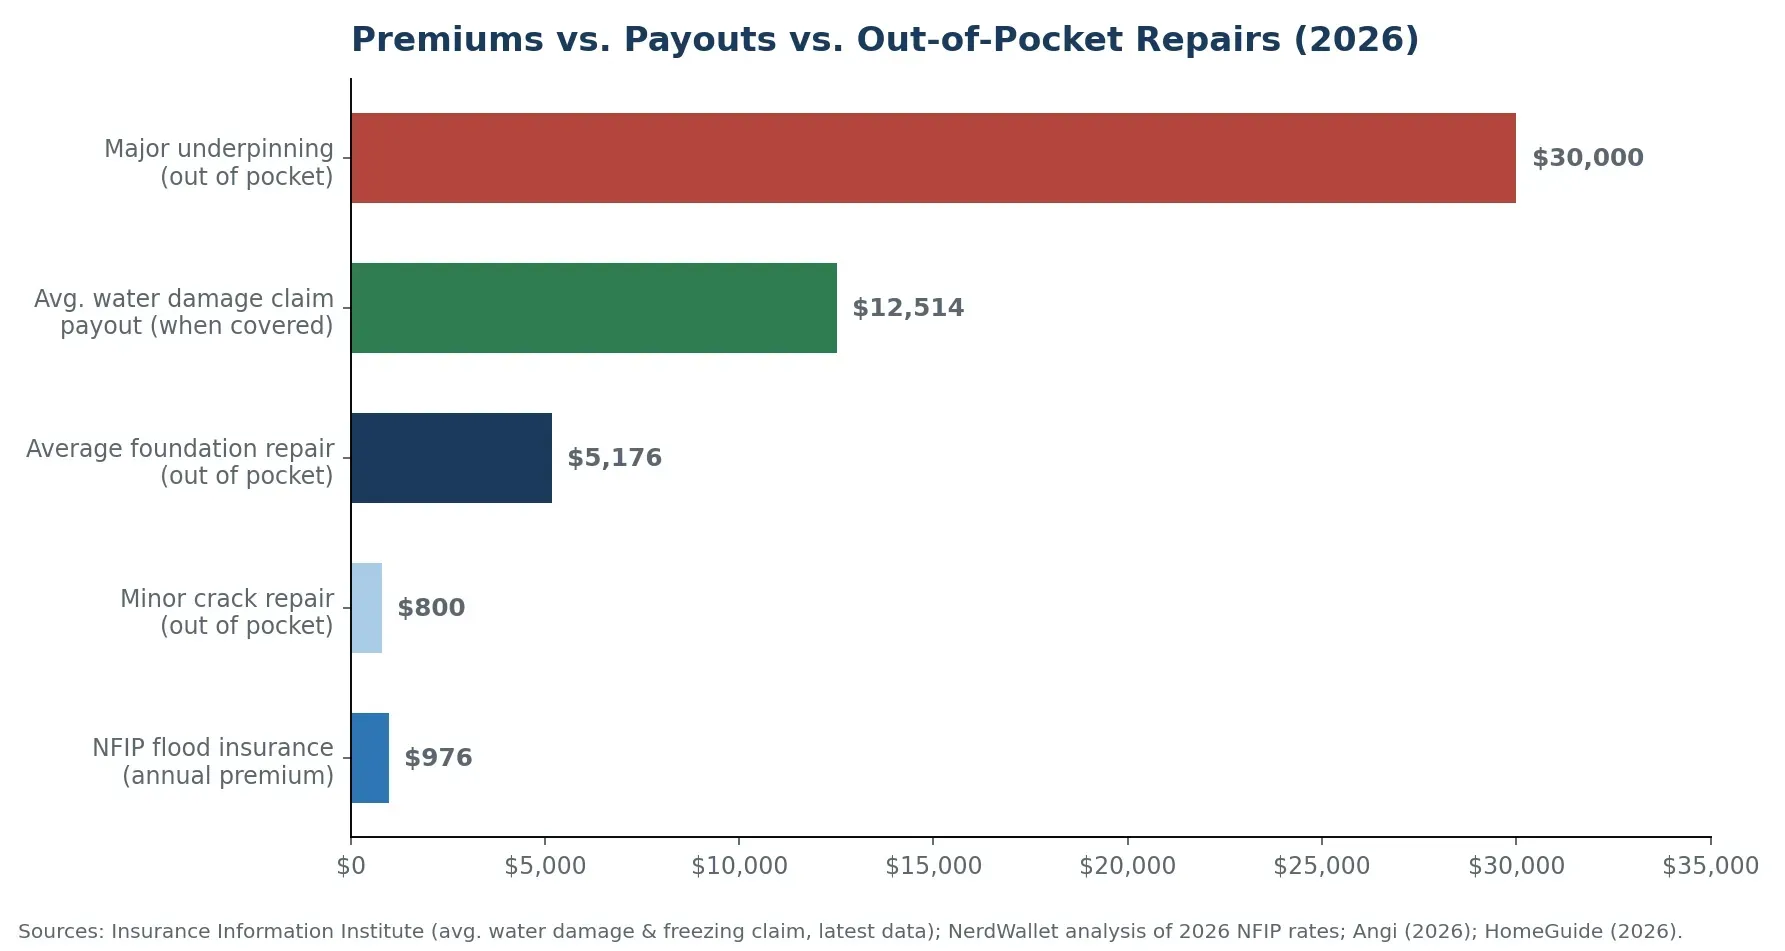
separate policies: NFIP flood insurance averages about
$976 per year in 2026. When coverage does apply, it matters: the average water damage and freezing claim pays out
$12,514, while the
national average foundation repair costs $5,176 out of pocket when insurance says no. For Houston homeowners on expansive clay, the practical rule is simple: document sudden events immediately, and budget for
foundation repair in Texas as a maintenance cost, not an insurable one.
Fast Facts
| Question | 2026 Answer | Source |
|---|---|---|
| Is the foundation part of dwelling coverage? | Yes, but only for named covered perils | Allstate, Nationwide (2026) |
| Sudden burst pipe under slab | Usually covered, incl. access to the slab | Progressive (2026) |
| Soil settling / earth movement | Excluded on standard policies | Allstate, TDI (2026) |
| Flood-caused foundation damage | Needs separate NFIP policy (~$976/yr avg.) | NerdWallet 2026 NFIP analysis |
| Earthquake-caused cracks | Needs separate earthquake policy | Nationwide (2026) |
| Texas slab endorsement | Foundation/water damage endorsement, often ~15% of dwelling limit | TX insurer guidance |
| Average covered water claim payout | $12,514 | Insurance Information Institute |
| Home warranty plans | Do not cover structural foundation repair | Industry guidance |
When Does Homeowners Insurance Cover Foundation Repair?
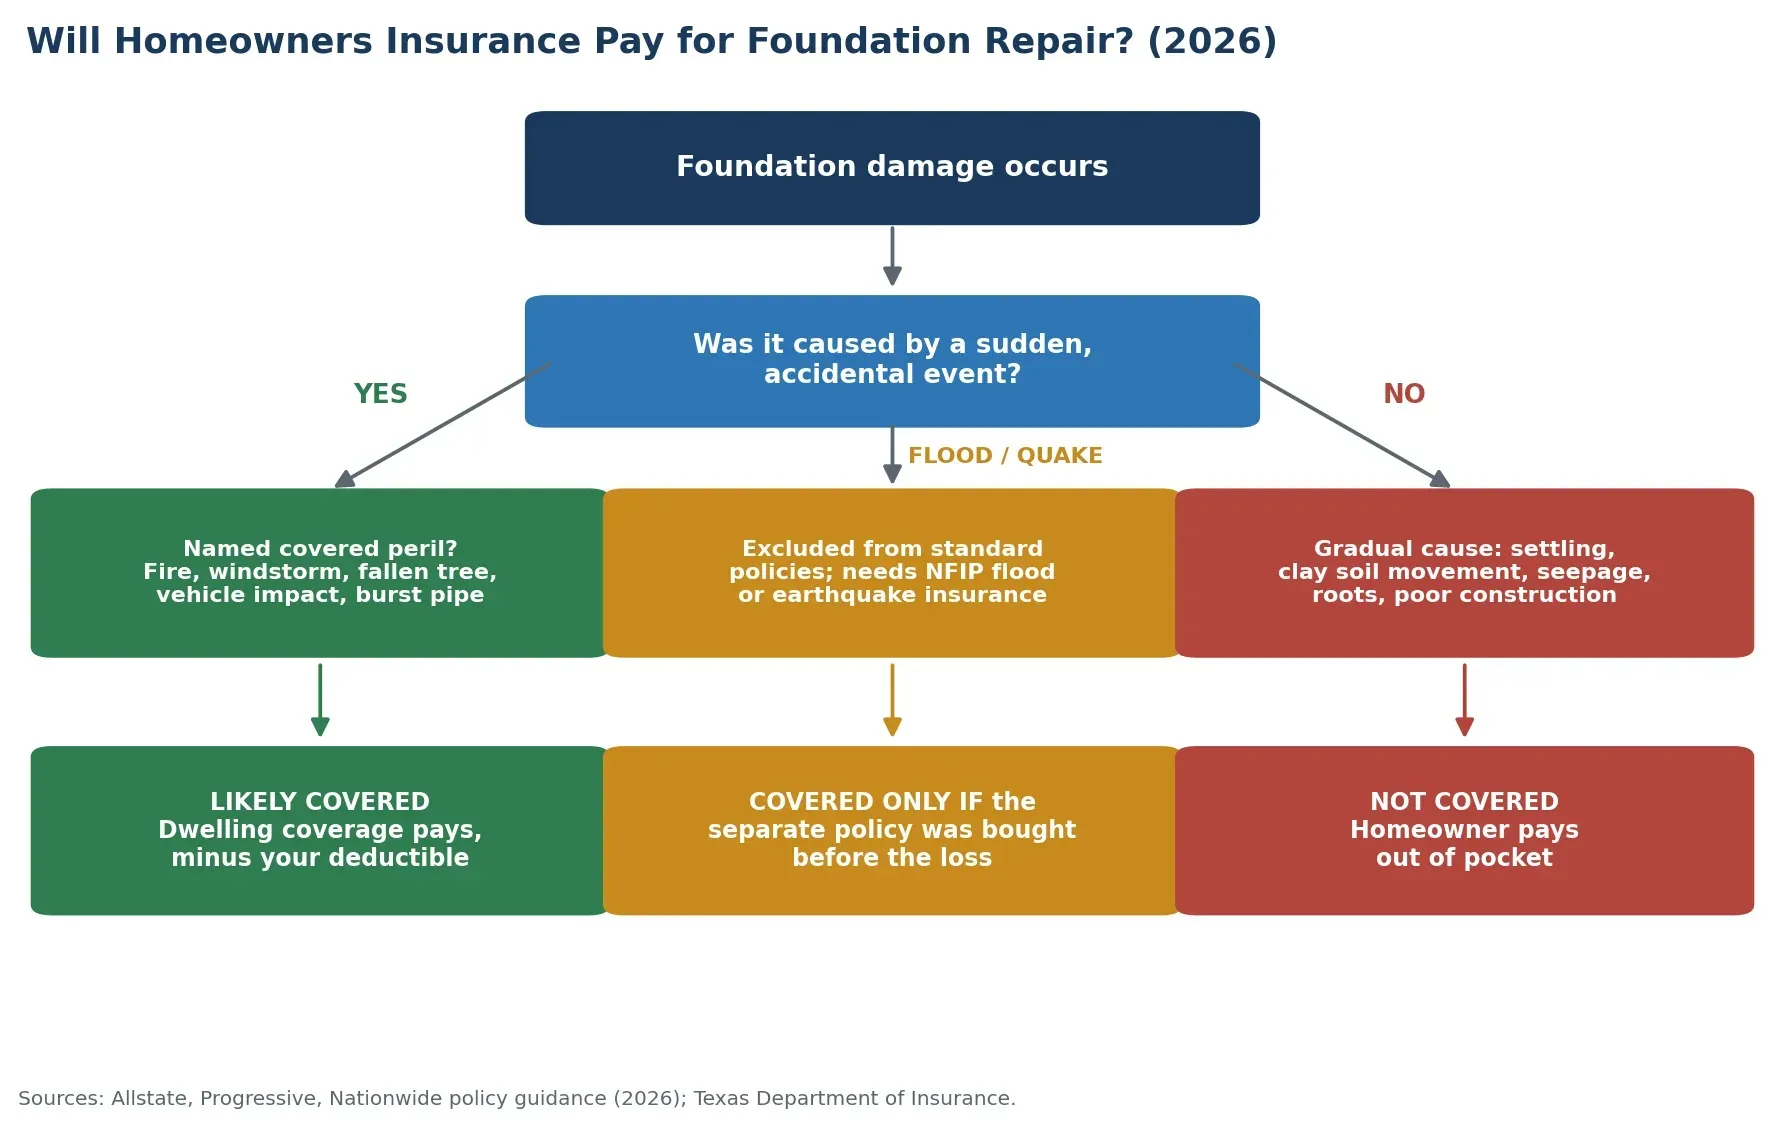
Your foundation is insured under the dwelling portion (Coverage A) of a standard homeowners policy, but only against the perils the policy names. The question adjusters ask is always the same: was the damage sudden and accidental, or gradual and preventable?
Covered situations are abrupt events outside your control. If a lightning fire cracks the slab, a windstorm drops a tree on the house, a car strikes the structure, or a pipe suddenly bursts beneath the foundation, dwelling coverage typically pays for structural repairs, minus your deductible. That can include tearing out and restoring concrete slab sections to reach a burst pipe.
In practice, though,
most foundation repairs are not covered, because most foundation damage comes from the ground: expansive clay soils swelling and shrinking, slow leaks eroding support, or normal settling as a house ages. Insurers classify all of that as maintenance.
| Scenario | Covered? | Why |
|---|---|---|
| House fire cracks foundation | Yes | Fire is a named peril on every standard policy |
| Tree falls and damages foundation | Yes | Falling objects are covered sudden accidents |
| Vehicle hits the house | Yes | Vehicle impact is a named peril |
| Pipe suddenly bursts under slab | Yes | Sudden accidental water discharge is covered |
| Flood undermines foundation | Separate policy | Construction defects are typically excluded; homeowner’s insurance isn’t a warranty. |
| Earthquake cracks the slab | Separate policy | Earth movement exclusion; quake policy required |
| Gradual soil settling cracks slab | No | Earth movement / wear and tear exclusion |
| Slow leak erodes soil under slab | No | Seepage over time is deemed preventable |
| Tree roots or termites damage foundation | No | Classified as a maintenance responsibility |
| Builder error causes cracking | No | Faulty workmanship exclusion; not a warranty |
What Foundation Issues Are Typically Excluded?
- Earth movement. Settling, shrinking, expansion, landslides, mudflow, and subsidence. If Houston clay dries out in a heatwave and a slab corner sinks, standard policies will not pay for piers or house leveling.
- Wear and tear. Cracks that develop over years as materials age are treated as normal home aging, not an insurable loss.
- Long-term leaks and seepage. Only sudden and accidental water discharge is covered. A pipe that dripped for months, or chronic moisture from poor drainage, is deemed preventable; correcting the cause with proper drainage solutions is the homeowner's job.
- Faulty construction or design. Inadequate rebar, shallow footings, or poor soil preparation fall on the builder or the homeowner, not the insurer.
- Pests and roots. Termite damage and invasive tree roots are maintenance exclusions. Early attention to foundation cracks keeps these problems small and cheap.
Most policies also carry a specific clause excluding “settling, cracking, bulging or expansion” of foundations, walls, and floors unless a covered event caused it. A crack that simply appears on its own is excluded by definition.
The Texas and Houston Rules
Texas insurers treat soil-driven slab damage as a known, expected risk and exclude it explicitly. The Texas Department of Insurance advises that standard policies will not pay for foundation damage from shifting soils or drainage problems, the two most common causes of foundation repair in Houston and across the state.
Two Texas-specific points matter:
- Foundation / water damage endorsement. Many Texas insurers sell an optional endorsement, commonly capped around 15% of your dwelling coverage limit, that pays for foundation damage caused by plumbing leaks under the slab. On a $300,000 dwelling limit, that is up to $45,000 of slab-leak protection, often for a modest annual premium. Ask your agent specifically for foundation or slab coverage.
- Maintenance expectations. Insurers expect Texas homeowners to manage soil moisture (soaker hoses, gutters, grading). Damage traced to neglected drainage is routinely denied, which is another reason prevention pays.
Flood, Earthquake, and Other Separate Coverage
| Coverage | What it does for foundations | 2026 cost snapshot |
|---|---|---|
| NFIP flood insurance | Covers structural foundation damage caused by flooding | ~$976/yr average (NerdWallet 2026 NFIP analysis) |
| Earthquake insurance | Covers quake-caused foundation cracks | Varies by state and deductible |
| TX foundation endorsement | Slab damage from plumbing leaks, often ~15% of dwelling limit | Modest add-on premium; ask your agent |
| Home warranty | Nothing: warranties cover systems and appliances, not structure | Not a foundation solution |
The math favors buying the right add-on before a loss. A flood policy near $1,000 per year is small next to an uninsured foundation rebuild, and in flood-prone Houston ZIP codes it is often the only path to coverage for water-undermined foundations.
How to File a Foundation Damage Claim
- Act fast and document. Photograph the damage and the cause the day you find it. Sudden events must look sudden in your file.
- Get cause-of-loss evidence. A plumber's report for a burst pipe, or an engineer's report tying cracks to a specific event, is what separates approved claims from denied ones. An independent structural foundation assessment documents movement, elevations, and probable cause.
- Stop further damage. Policies require reasonable steps to prevent worsening (shutting off water, tarping). Keep receipts; mitigation costs are usually reimbursable.
- Know your deductible and limits. Foundation work is expensive; confirm the payout math before accepting a quick settlement.
- Appeal denials with evidence. If the adjuster calls it gradual and your engineer disagrees, request a re-inspection and submit the report. Texas policyholders can also complain to TDI.
If the Claim Is Denied: Planning the Repair Yourself
Most foundation repairs end up self-funded, so benchmark the numbers before signing anything. The 2026 national average is $5,176, minor crack sealing runs $250 to $800, and major underpinning reaches $10,000 to $30,000+. Get at least three itemized bids, and use financing options such as contractor payment plans, a HELOC, or an FHA Title I loan (up to $25,000 for structural repairs) rather than deferring: deferred foundation problems compound.
Frequently Asked Questions
Does homeowners insurance cover foundation repair?
Only when a sudden, covered peril causes the damage, such as a fire, windstorm, fallen tree, vehicle impact, or burst pipe. Gradual damage from settling, soil movement, seepage, roots, or construction defects is excluded on standard policies.
Does insurance cover foundation cracks from settling?
No. Settling, shrinking, bulging, and expansion of foundations are specifically excluded as earth movement and wear and tear. Homeowners pay for settlement repairs out of pocket.
Does homeowners insurance cover slab leaks in Texas?
A sudden burst pipe under the slab is usually covered, including access through the slab. Slow leaks are not. Many Texas insurers also offer a foundation or water damage endorsement, often around 15% of your dwelling limit, that covers slab damage from plumbing leaks.
Will insurance pay for foundation damage from a flood or earthquake?
Not under a standard policy. Both require separate coverage: NFIP flood insurance (about $976 per year on average in 2026) or an earthquake policy purchased before the loss.
What should I do if my foundation claim is denied?
Get an independent structural engineer's report on the cause of damage, request a re-inspection, and appeal with that evidence. If the damage is genuinely gradual, plan the repair yourself: the 2026 national average is $5,176, and financing options exist for larger jobs.
Methodology
This report synthesizes 2026 coverage guidance from major insurers (Allstate, Progressive, Nationwide, Farmers), federal program data (FEMA/NFIP, HUD), the Insurance Information Institute's claim statistics, NerdWallet's 2026 NFIP rate analysis, and Texas Department of Insurance consumer guidance, cross-checked against 2026 repair cost data from Angi and HomeGuide.
Sources
1. Allstate: Does Homeowners Insurance Cover Foundation Issues? (https://www.allstate.com/resources/home-insurance/foundation-repair)
2. Progressive: Does Home Insurance Cover Foundation Repairs? (https://www.progressive.com/answers/does-home-insurance-cover-foundation/)
3. Nationwide: Does Homeowners Insurance Cover Foundation Repair? (https://www.nationwide.com/lc/resources/home/articles/does-homeowners-insurance-cover-foundation-repair)
4. Farmers: Does Home Insurance Cover My Foundation? (https://www.farmers.com/learn/insurance-questions/does-home-insurance-cover-my-foundation/)
5. U.S. News: Does Home Insurance Cover House Foundation Repair? (https://www.usnews.com/insurance/homeowners-insurance/does-home-insurance-cover-house-foundation-repair)
6. Insurance Information Institute via ConsumerAffairs: Water Damage Claims Statistics 2026 (https://www.consumeraffairs.com/homeowners/water-damage-insurance-claims-statistics.html)
7. NerdWallet: Flood Insurance Cost, 2026 NFIP Rates (https://www.nerdwallet.com/insurance/homeowners/learn/flood-insurance-cost)
8. FEMA: NFIP Flood Insurance Pricing (https://www.fema.gov/flood-insurance/work-with-nfip/risk-rating/single-family-home)
9. Texas insurer guidance: Is Your Foundation Covered by Your Texas Homeowners Policy? (https://www.insurancefortexans.com/blog/is-your-foundation-covered-by-your-texas-homeowners-insurance-policy)
10. Insuranceopedia: Does Homeowners Insurance Cover Slab Leak Repair? (https://www.insuranceopedia.com/homeowners-insurance/does-homeowners-insurance-cover-slab-leak)
11. HUD: Title I Property Improvement Loan Program (https://www.hud.gov/hud-partners/single-family-title)
12. Angi: How Much Does Foundation Repair Cost? (2026) (https://www.angi.com/articles/how-much-does-foundation-repair-cost.htm)
13. HomeGuide: Foundation Repair Cost (2026) (https://homeguide.com/costs/foundation-repair-cost)
This article is for informational purposes only and does not constitute insurance, legal, or financial advice. Coverage varies by policy and state; confirm details with your insurer. For repair questions, consult a licensed
foundation repair specialist.